 how-to
Owner Finance Real Estate: How It Works & What You Need
Last Updated: October 23, 2026
Quick Summary
Owner finance real estate is when a property seller acts as the lender instead of a bank, with the buyer making a down payment and paying the seller monthly until the property is paid off. This bypasses bank approval and credit checks, allowing self-employed individuals, ITIN holders, and those with poor credit to become homeowners.
- Down payments typically range from 10-30% of the purchase price
- Owner-financed interest rates are typically 5-10%, negotiated between buyer and seller
- Loan terms commonly range from 5 to 30 years with fixed monthly payments
- The buyer receives the deed and becomes owner of record immediately at closing
- Buyers must verify the seller owns the property free and clear to avoid due-on-sale complications
Table of Contents
- What Is Owner Financing and How Does Owner Financing Work
- Owner Financing Requirements: What Sellers and Buyers Need to Qualify
- The Owner Financing Agreement: Promissory Notes, Mortgages, and Deeds of Trust
- Owner Financing Pros and Cons: Benefits and Risks for Both Parties
- Down Payments, Interest Rates, and Repayment Terms
- The Owner Financing Process: From Offer to Closing and Beyond
- Critical Risks: Existing Mortgages, Due-on-Sale Clauses, and Default Scenarios
- Conclusion
- Frequently Asked Questions
What Is Owner Financing and How Does Owner Financing Work
Owner financing is when a property seller acts as the lender instead of a bank.
At Sold With Financing, we empower aspiring homeowners to achieve their dreams through owner financing when traditional lenders reject them.
Unlike a conventional mortgage, the seller holds the note and security interest, while the buyer becomes owner of record immediately, the deed goes into their name at closing, so you own the home from day one.
The Basic Transaction Structure
In an owner finance real estate deal, the seller finances part of the purchase price and the buyer repays that amount over an agreed timeframe with interest.
The transaction structure includes three core elements:
- Down payment: The buyer pays the seller upfront (typically 10-30% of the purchase price)
- Promissory note: A legal document stating the loan amount, interest rate, and repayment schedule
- Security instrument: A mortgage or deed of trust that gives the seller the right to foreclose if the buyer defaults
The buyer takes title immediately, can live in and refinance the property, while the seller holds a lien as security.
How Payments and Terms Are Arranged
Buyer and seller negotiate terms directly, with no lender dictating what's acceptable, which is why owner financing works for people banks reject.
Common payment structures include:
- Amortized loans: Fixed monthly payments over 5-30 years, with interest included
- Interest-only periods: Early payments cover only interest; principal comes later
- Balloon payments: Smaller monthly payments with a large lump sum due at the end (though Sold With Financing avoids these)
The seller sets the interest rate based on market conditions, the buyer's situation, and property value, typically 5-10%, depending on what both parties agree to.
Owner Financing Requirements: What Sellers and Buyers Need to Qualify
Buyer Qualification Criteria
Banks use credit scores, debt-to-income ratios, and employment verification. Owner financing uses different criteria because the seller takes the risk.
Typical buyer requirements include:
- Down payment: Usually 10-30% of the purchase price in cash
- Income verification: Proof of stable income (pay stubs, tax returns, bank statements)
- Credit history: Not required, though a poor history may mean higher interest rates
This is why owner financing works for self-employed individuals, ITIN holders, people with past foreclosures, and those with low credit scores.
Sold With Financing qualifies buyers on income and down payment, with no minimum credit score.
Seller Requirements and Property Eligibility
Not every property or seller qualifies for owner financing, since lenders impose restrictions on the seller.
Key seller requirements:
- Own the property free and clear (or have lender permission to finance)
- No due-on-sale clause that blocks financing (or willingness to accept the risk)
- Property must be in acceptable condition for the buyer to occupy
The property must be a single-family home, condo, or multi-unit in livable condition; commercial, land-only, and severely distressed properties are harder to finance this way.
If the seller still owes on a mortgage, the existing lender's due-on-sale clause could trigger, a critical risk addressed below.
The Owner Financing Agreement: Promissory Notes, Mortgages, and Deeds of Trust
What Goes Into a Promissory Note
A promissory note is a written promise to repay the loan. It's the legal foundation of the owner financing agreement.
The note includes:
- Loan amount: The principal the buyer is borrowing
- Interest rate: The percentage charged annually
- Loan term: How many years the buyer has to repay
Signed by both parties, the note is a binding contract and legal proof of the debt.
Sold With Financing ensures every promissory note is clear and protects both parties, with fixed monthly payments and no hidden fees or prepayment penalties.
Security Instruments: Mortgages vs. Deeds of Trust
The promissory note creates the debt. A security instrument gives the seller the right to take back the property if the buyer defaults.
In some states, a deed of trust is used instead: a neutral trustee can foreclose without a lawsuit, often in 60-120 days, and the property is sold to recover the debt.
Both protect the seller; the choice depends on state law.
Owner Financing Pros and Cons: Benefits and Risks for Both Parties
Advantages for Buyers
Owner financing opens doors that traditional lenders keep closed. Buyers gain:
- No credit score requirement: Sellers focus on income and down payment
- Faster approval: Decisions happen in days, not weeks
- Flexible qualification: Self-employed income, ITIN status, and past foreclosures don't automatically disqualify you
Advantages for Sellers
Sellers benefit too: owner financing expands their buyer pool and generates income.
- Larger buyer pool: Access to buyers banks reject expands your market
- Monthly income stream: Payments with interest instead of a lump sum
- Higher sale price: Sellers often charge more to compensate for risk
Risks and Drawbacks to Consider
Owner financing isn't risk-free. Both parties face real downsides.
Buyer risks:
- Higher interest rates: Owner-financed loans typically cost more than bank mortgages
- Shorter loan terms: Many deals run 5-15 years, not 30
- Due-on-sale complications: If the seller still owes a bank, the bank may force payoff when the property changes hands
Seller risks:
- Default risk: The buyer may stop paying; foreclosure takes months and costs money
- Property damage: Limited recourse until foreclosure
- Vacancy risk: The property may sit empty during foreclosure
Down Payments, Interest Rates, and Repayment Terms
Typical Down Payment Amounts
Down payments typically range from 10-30% of the purchase price. A larger down payment means lower monthly payments and less total interest for the buyer, and more cash and lower risk for the seller. Buyers with strong savings often put down 20-30%; those with limited savings might negotiate 10-15%.
At Sold With Financing, we focus on your income and down payment for flexible qualification.
How Interest Rates Are Set
Interest rates are negotiated between buyer and seller, with no fixed market rate. Factors include current mortgage rates (if banks charge 6%, owner-financed rates are often 6-8%), the buyer's risk profile, loan term, down payment size, property condition, and market conditions. Owner-financed rates typically fall between 5-10%.
Loan Terms and Monthly Payment Calculations
Loan terms vary widely: 5-year terms mean higher payments but faster payoff; 10-year terms are a common middle ground; 15-year terms lower payments further; 20-30 year terms mirror traditional mortgages with the lowest payments.
To calculate a monthly payment, use this formula:
Monthly Payment = [Loan Amount × (Interest Rate ÷ 12)] ÷ [1 − (1 + Interest Rate ÷ 12)^(−Number of Months)]
Here's a practical example:
- Purchase price: $250,000
- Down payment: $50,000 (20%)
- Loan amount: $200,000
Over 15 years, you pay $284,400 total ($1,580 × 180 months); the $84,400 difference is the interest cost.
| Loan Term | Monthly Payment | Total Interest Paid | Total Amount Paid |
|---|---|---|---|
| 5 years | $3,869 | $31,140 | $231,140 |
| 10 years | $2,125 | $55,000 | $255,000 |
| 15 years | $1,580 | $84,400 | $284,400 |
| 20 years | $1,295 | $110,800 | $310,800 |
(Based on $200,000 loan at 6.5% interest)
The Owner Financing Process: From Offer to Closing and Beyond
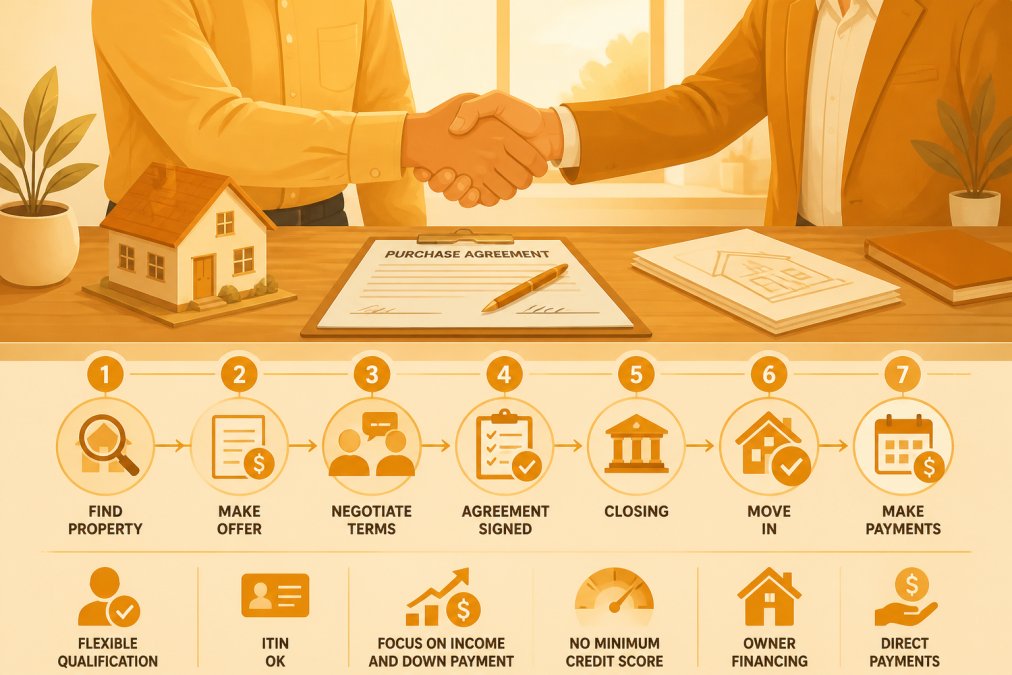
Step 1: Find a Property and Make an Offer
Start by identifying a property the seller is willing to finance, not all sellers offer it, so ask directly or work with an agent who understands the market. Your offer should state the purchase price, down payment, requested loan term (5, 10, 15, 20, or 30 years), interest rate range, and closing date.
Step 2: Negotiate Terms and Structure the Deal
If the seller is interested, you negotiate the actual terms: purchase price, down payment, loan amount, interest rate, loan term, monthly payment, late fees, and default terms. Both parties should have legal representation to protect their interests and ensure compliance with state law.
Step 3: Complete Due Diligence and Title Work
Before closing, verify the property's condition and the seller's right to sell. Due diligence includes a property inspection, an appraisal, a title search (to confirm the seller owns it free and clear or reveal existing liens), a survey if needed, and insurance quotes. Title work is critical: if the seller still owes a bank, the title search reveals it and triggers the due-on-sale discussion.
Step 4: Sign Documents and Close
At closing, documents are signed and ownership transfers: the promissory note, the mortgage or deed of trust, the deed, a closing disclosure, and title insurance. Closing happens at a title company or attorney's office, where the deed is recorded in your name and the security instrument in the seller's. You become owner of record at closing.
Step 5: Begin Making Payments
After closing, you make monthly payments to the seller per the promissory note. Each payment includes principal and interest; early payments are mostly interest, later ones mostly principal (standard amortization). You're responsible for property taxes, homeowner's insurance, maintenance and repairs, and HOA fees. The seller is no longer involved in day-to-day ownership.
Critical Risks: Existing Mortgages, Due-on-Sale Clauses, and Default Scenarios
Understanding Due-on-Sale Clauses
A due-on-sale clause in most mortgages requires the entire loan balance to be paid off when the property is sold or transferred.
Example:
- Seller owns a home worth $300,000
- Seller still owes $150,000 to their bank
- Seller agrees to owner finance the home to you for $280,000
If the seller can't pay off the bank, the bank forecloses and your ownership is at risk.
Sold With Financing verifies clear title before any deal closes. We don't put buyers in jeopardy from existing mortgages.
What Happens If You Default
If you stop making payments, the seller can foreclose and you lose your home and down payment. Default typically happens after 30-60 days of missed payments; the seller sends a notice of default and you get a cure period (usually 30 days). If you don't cure it, foreclosure begins: with a mortgage, the seller files a lawsuit (6-12 months); with a deed of trust, the trustee sells the property (60-120 days).
Conclusion
Owner finance real estate removes barriers traditional lenders create. It's built on income and down payment capacity, not credit scores or employment verification, making homeownership possible for self-employed individuals, ITIN holders, people with past foreclosures, and those with low credit scores.
Sold With Financing specializes in owner financing for buyers traditional lenders reject. We verify clear title, structure deals fairly, eliminate balloon payments, and close fast. See if you qualify by connecting with our team today.
Frequently Asked Questions
How does owner financing work when buying a home?
In owner financing, the property seller acts as the lender instead of a bank. The buyer makes a down payment and then pays the seller monthly installments plus interest over an agreed-upon term. The buyer receives the deed at closing and becomes the owner of record immediately, while the seller holds a promissory note and mortgage or deed of trust as security. This arrangement bypasses traditional mortgage lenders and their credit score requirements.
What qualifications do buyers need for owner financing?
Owner financing requirements vary by seller but typically focus on income stability and down payment capacity rather than credit scores. Most sellers want proof of consistent income (W-2s, tax returns, bank statements, or business income documentation), a down payment of 10-30% of the purchase price, and verification that you can afford the monthly payments. ITIN holders and self-employed individuals are often eligible. Sellers may also conduct a background check or review your financial history.
What is included in an owner financing agreement?
An owner financing agreement includes a promissory note (the loan terms: amount, interest rate, monthly payment, and duration) and a security instrument (either a mortgage or deed of trust, depending on state law). The agreement specifies what happens if payments are missed, whether the buyer can refinance or pay off early, property tax and insurance responsibilities, and any balloon payment terms. All documents must comply with state law and clearly define both parties' rights and obligations.
Can you pay off an owner-financed loan early without penalty?
Whether you can pay off early without penalty depends on the terms negotiated in your specific financing agreement. Sold With Financing offers the ability to refinance or pay off early without penalty, as stated in our key features. Always clarify this point in writing during negotiations to avoid surprises.